
Enterprise-grade lenders — national banks, the GSEs, the top-25 independent mortgage banks — do not evaluate mortgage tech vendors the way a regional credit union does. The review runs deeper, the integrations are harder, the compliance expectations are heavier, and the commercial terms sit in a different league. A startup that wins regionally can still be disqualified at the enterprise level for reasons that have nothing to do with how good the product is.
What follows is the current shape of that bar, drawn from 40+ mortgage technology engagements. Treat each section as a gate. Miss one and procurement stalls.
Compliance Is Layered, Not Single-Framework
Mortgage tech sits under more overlapping regimes than most verticals. Federal consumer protection alone spans TILA, RESPA, TRID, HMDA, ECOA and Fair Housing, with CFPB-aligned UDAAP guidance on top. Add state licensing and notification obligations, GLBA for consumer financial data, and — if you touch servicing at all — Regulation X and the CFPB’s servicing rules.
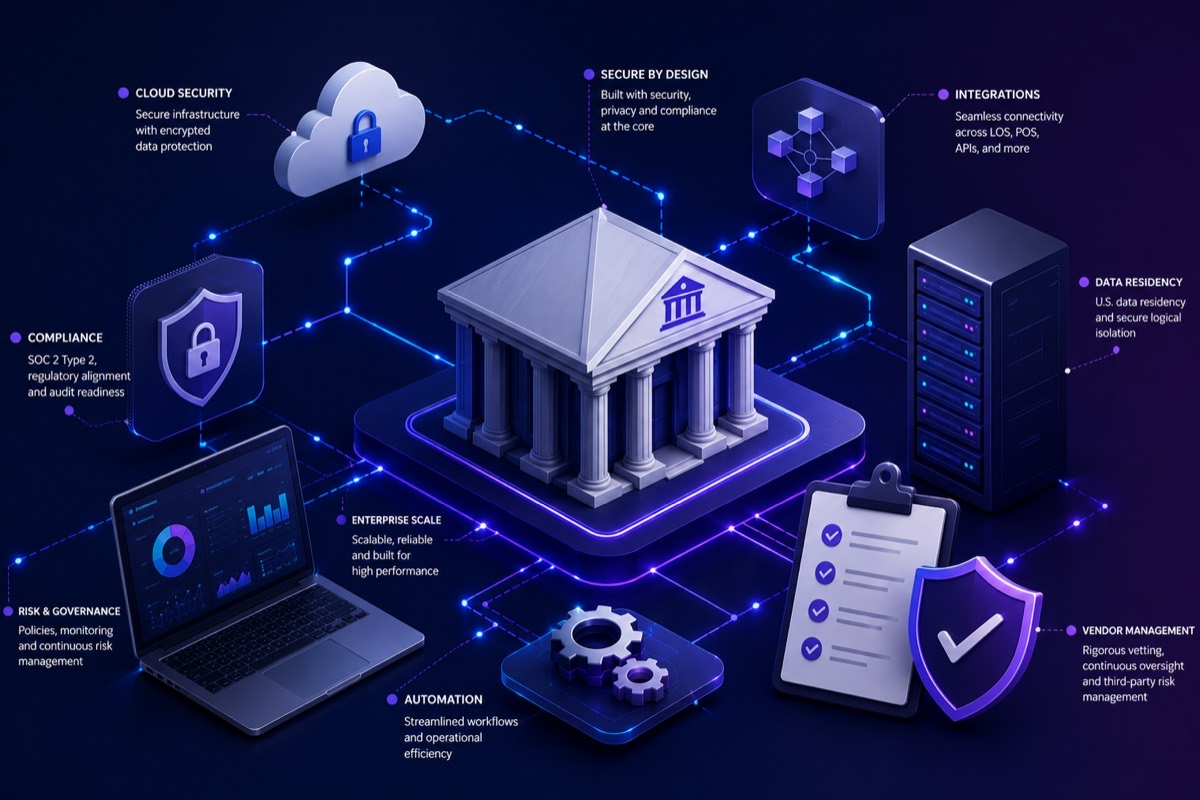
Layered above that is the enterprise stack proper: SOC 2 Type 2, ISO 27001 alignment, and a NIST 800-53 moderate baseline for lenders selling to the GSEs.
SOC 2 is the entry ticket, and the word “entry” is doing real work. Without a Type 2 report, an enterprise lender cannot begin the substantive compliance review. The vendor risk team disqualifies the package at triage, before anyone technical looks at your product.
So compliance belongs in sprint one, not in the first procurement conversation. Retrofitting regulatory controls onto a live codebase is where most enterprise mortgage deals actually die — not because the product was wrong, but because the compliance surface turned out to be larger than the engineering surface.
Integration: LOS, POS, Servicing, Secondary
Enterprise lenders run on a dense stack: one or more loan origination systems — Encompass, Blue Sage, Lending QB, MeridianLink, Calyx — a consumer-facing point-of-sale layer, servicing platforms, document management, pricing engines, and secondary market platforms for delivery. Landing in that stack means integrating cleanly with at least two of those, usually more.
None of it is standardised. Encompass offers a modern API and a legacy SDK with genuinely different integration stories. Servicing platforms still lean on batch files and legacy SOAP. The GSE integrations — Fannie Mae’s DU, Freddie Mac’s LPA, Desktop Underwriter, Loan Prospector — each carry their own ceremonies and test harnesses.
Architecture reviews expose this quickly. A vendor who cannot talk about adapter architecture, idempotent workflow design, or state reconciliation across systems of record in specific terms will not survive the conversation. Lenders are buying domain depth, not generalist engineering.
Data Residency and Tenancy
Lenders are conservative about where mortgage data lives. Expect US data residency requirements, increasingly explicit cloud region constraints, and periodic demands for dedicated infrastructure or bring-your-own-cloud deployment.
Your tenancy model — shared multi-tenant, logical isolation, or dedicated infrastructure — is not a sales conversation. It is a design decision that has to be settled before your first lender deal, because retrofitting dedicated tenancy onto a shared schema is a migration, not a configuration change.
Data classification and retention need the same rigour. Mortgage loan data is GLBA-covered consumer financial data, retention schedules differ by document type, and lenders will expect yours to line up with their own record retention policy.
Vendor Qualification Is a Long Form
Enterprise qualification is an exercise in evidence. Expect a security questionnaire running past 300 lines, based on SIG or an internal framework, plus separate reviews for financial stability, business continuity, Patriot Act and AML exposure on the company and its principals, privacy, vendor concentration, and model audit alignment where OCC or NAIC-adjacent guidance applies.
Every one of those wants proof. SOC 2 Type 2 covers a meaningful share. The remainder has to come from documented policies, tested runbooks, audited financials or a credible statement package, executed DPAs with your sub-processors, and a clear account of how you manage your own vendors.
The Twelve-Month Shape
A startup aiming at enterprise lenders inside a year is looking at compliance-first engineering and SOC 2 pipeline stand-up through the first quarter, core LOS and GSE integrations built alongside product from month two, the Type 2 observation window running roughly months four through nine, and design-partner engagements with InfoSec and procurement moving in parallel from month six. First signed enterprise contract lands somewhere in months nine to twelve.
That schedule is tight, and it only holds if engineering, compliance and integration run concurrently from day one. Which is precisely why we run those three disciplines as one accountable team rather than three sequential phases.
Where Reslt AI Plugs In
We build mortgage technology for lenders, servicers and mortgage platforms — including a customer whose lending platform our team builds and operates end to end, origination through servicing, with secure credit-bureau and lending-partner integrations underneath it.
The pattern is architecture-led, compliance-first and integration-pragmatic: a US architect who has sat on GSE review calls, a pod that has wired Encompass and DU integrations before, and a compliance engineer who has taken the pipeline through an enterprise lender’s vendor review rather than reading about one.
Doing this cold costs quarters and lost deals. Doing it with people who have already walked the path is a different calculation entirely — because at the top of this market, design is compliance, integration depth and domain fluency, bundled into how the work gets delivered.
Related reading: Mortgage Automation & Digital Origination in 2026 · Vendor Security Assessment: What Buyers Ask
Talk to Reslt AI
If this matches your next 12 months, Reslt AI can help: AI-Powered Test Automation, LLM Assurance and Governance Readiness for mortgage and insurance, the Data Exchange Engine for MISMO, and product engineering for the wider build — all inside your environment. Discuss your use case with our team.